Partners & employeesالشركاء والموظفون
Partners and employees are auxiliary accounts too. The same record, on the same Auxiliary Accounts screen, as every client and supplier. Only the account underneath them changes.
The owner is a partner, never a customer
This is the single most common thing to get wrong when a company is first set up, and it is worth being blunt about: the owner's own account is a partner account, not a customer account and not a supplier account.
The owner's current account - the money they put in and the money they draw out - belongs on 4515, the partners' current account, under 45 Partners. Booking it as a customer makes the owner look like a debtor, inflates receivables, and corrupts every ageing and top-10 report you will ever run.
Which sub-account under 4515 a given partner lands on is not worth agonising over. Getting them on a partner account is the decision that matters; an auxiliary record's account can be changed afterwards, which is not true of the chart's own parent/child structure.
Where they sit in the chart
Both families are children of class 4 Payables And Receivables:
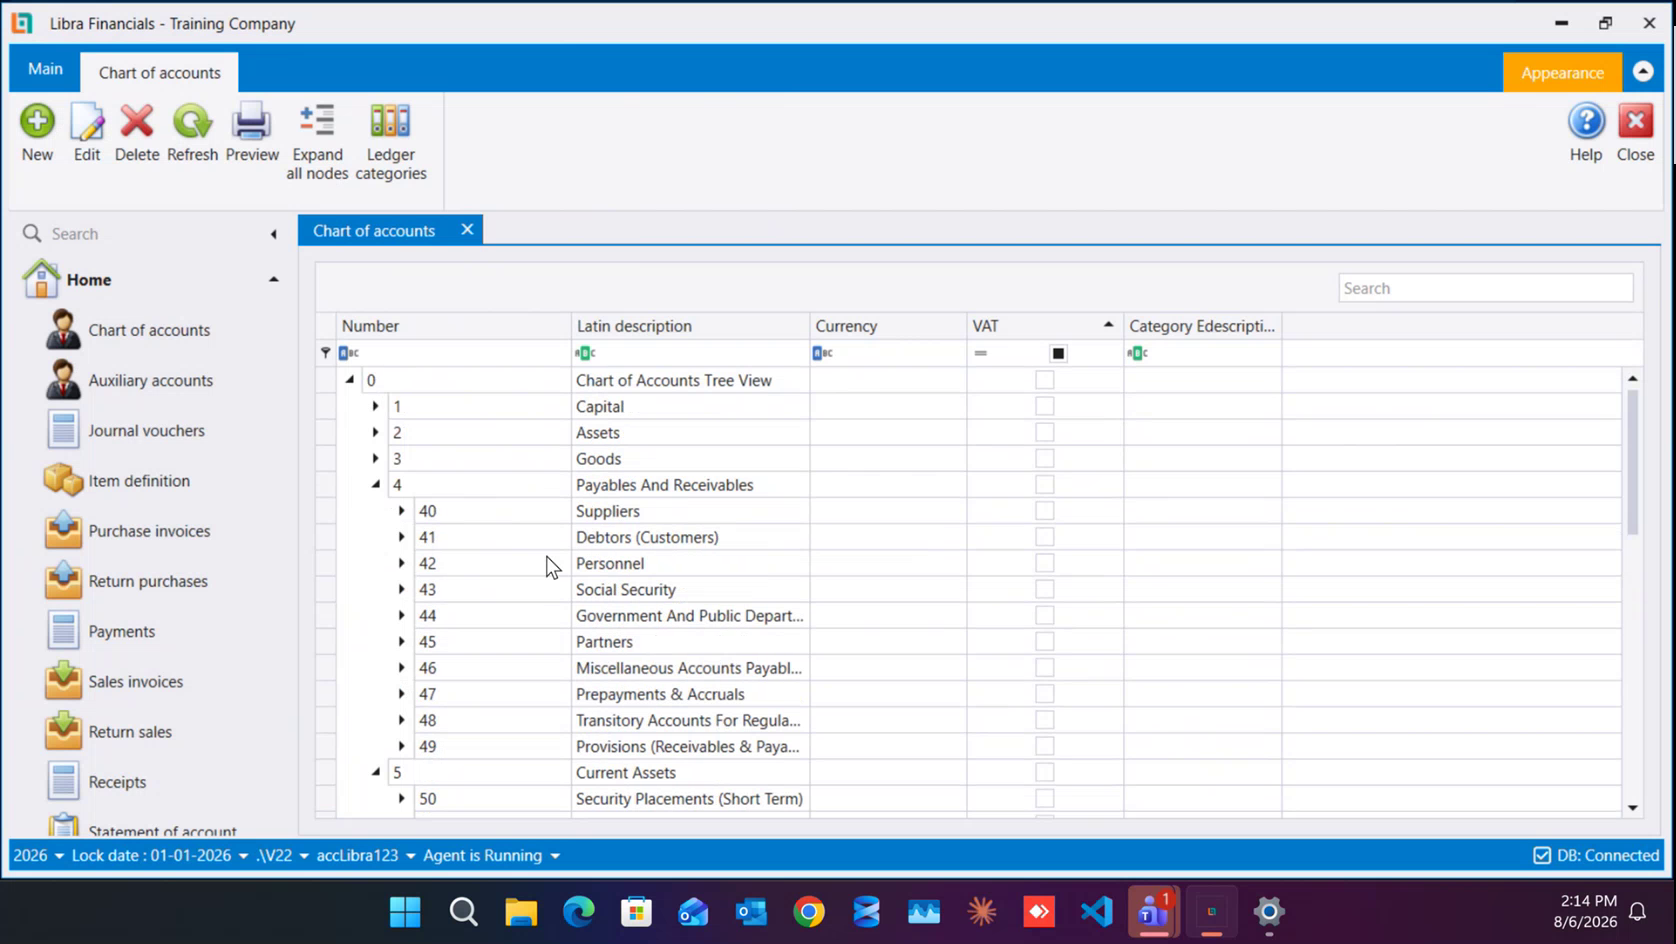
| Branch | What it holds |
|---|---|
| 42 Personnel | staff. 4212 Personnel is the account employee records point at - choose the employee list on an auxiliary record and it is the only account offered. The instructor also names 421 as the employees group sitting between the two |
| 43 Social Security | the social-security side, kept separate from staff pay |
| 44 Government And Public Departments | the state, including the VAT accounts |
| 45 Partners | the owners. 4515 is the partners' current account |
Employees
Open one auxiliary record per employee, on the employee account. Salaries and staff balances then run through that account, and each person has their own statement.
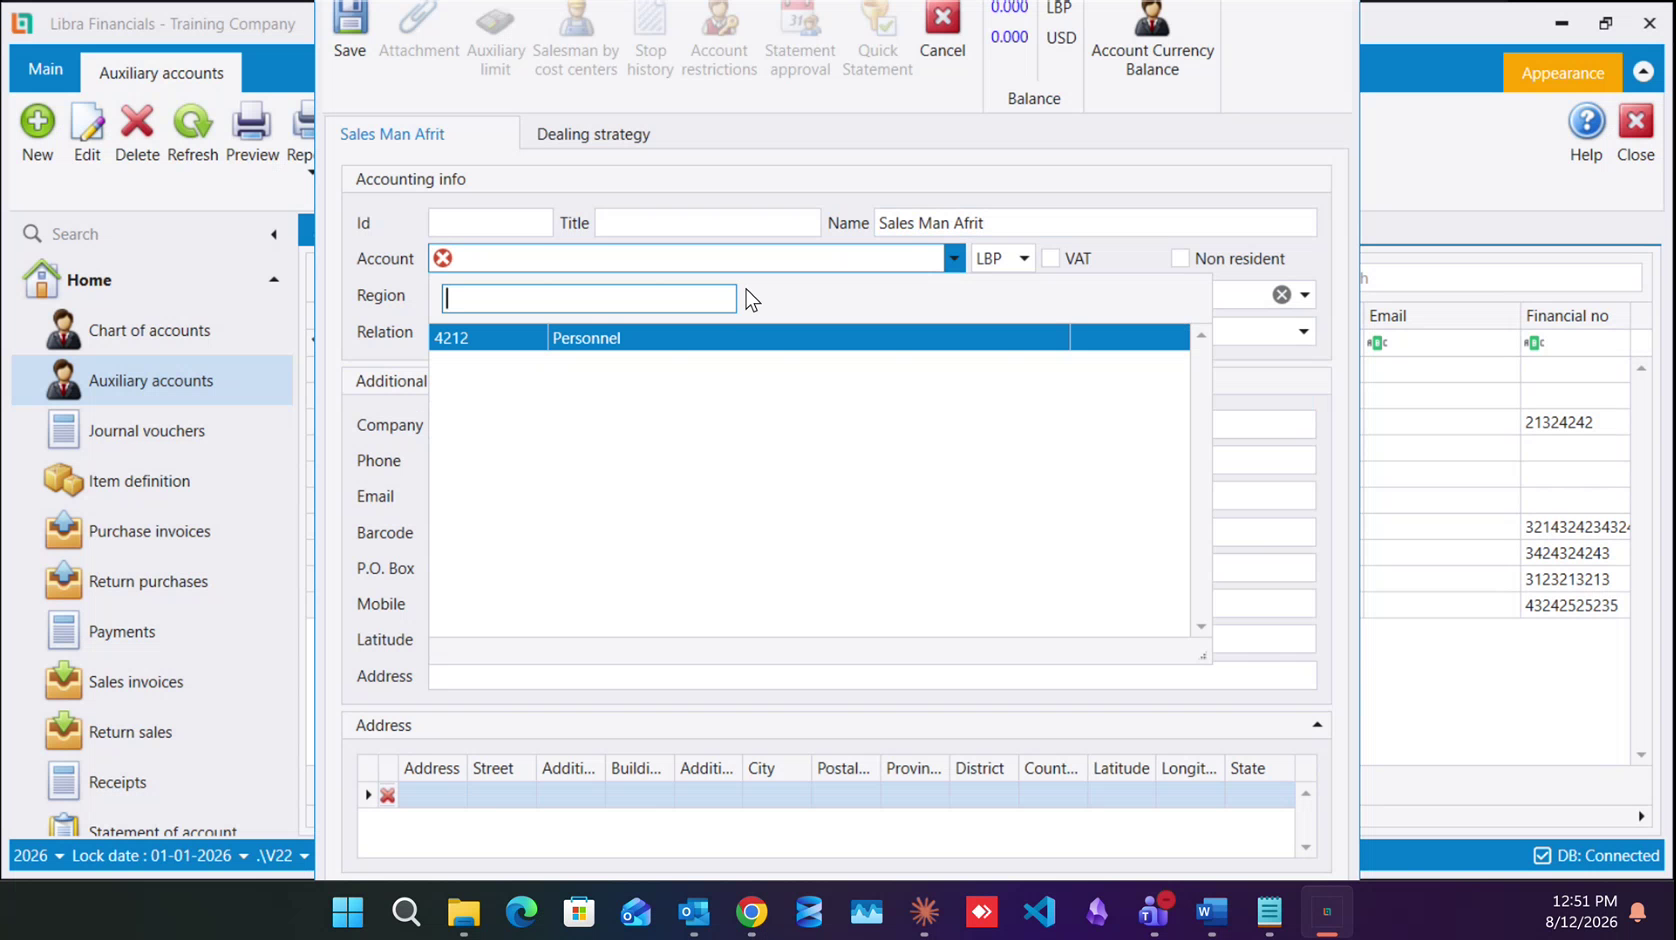
The List is what narrows the Account. On the auxiliary record, choose the employees list first. When you then open the Account picker, 4212 Personnel is the only account it offers - so there is no way to file an employee anywhere else by accident:
That is the same List → Account mechanic every party type uses; only the resulting shortlist differs. See the Auxiliary Accounts screen.
Note the difference between the account and the record: the account is one chart row shared by all staff; the record is one auxiliary per person. The same is true of partners.
Name them to a convention and stick to it. Because every employee shares one account, the record Name is the only thing distinguishing one person from another in a statement or a report. Decide the form before you open the first one - the training pauses to settle exactly this before creating any staff record.
One screen, every party type
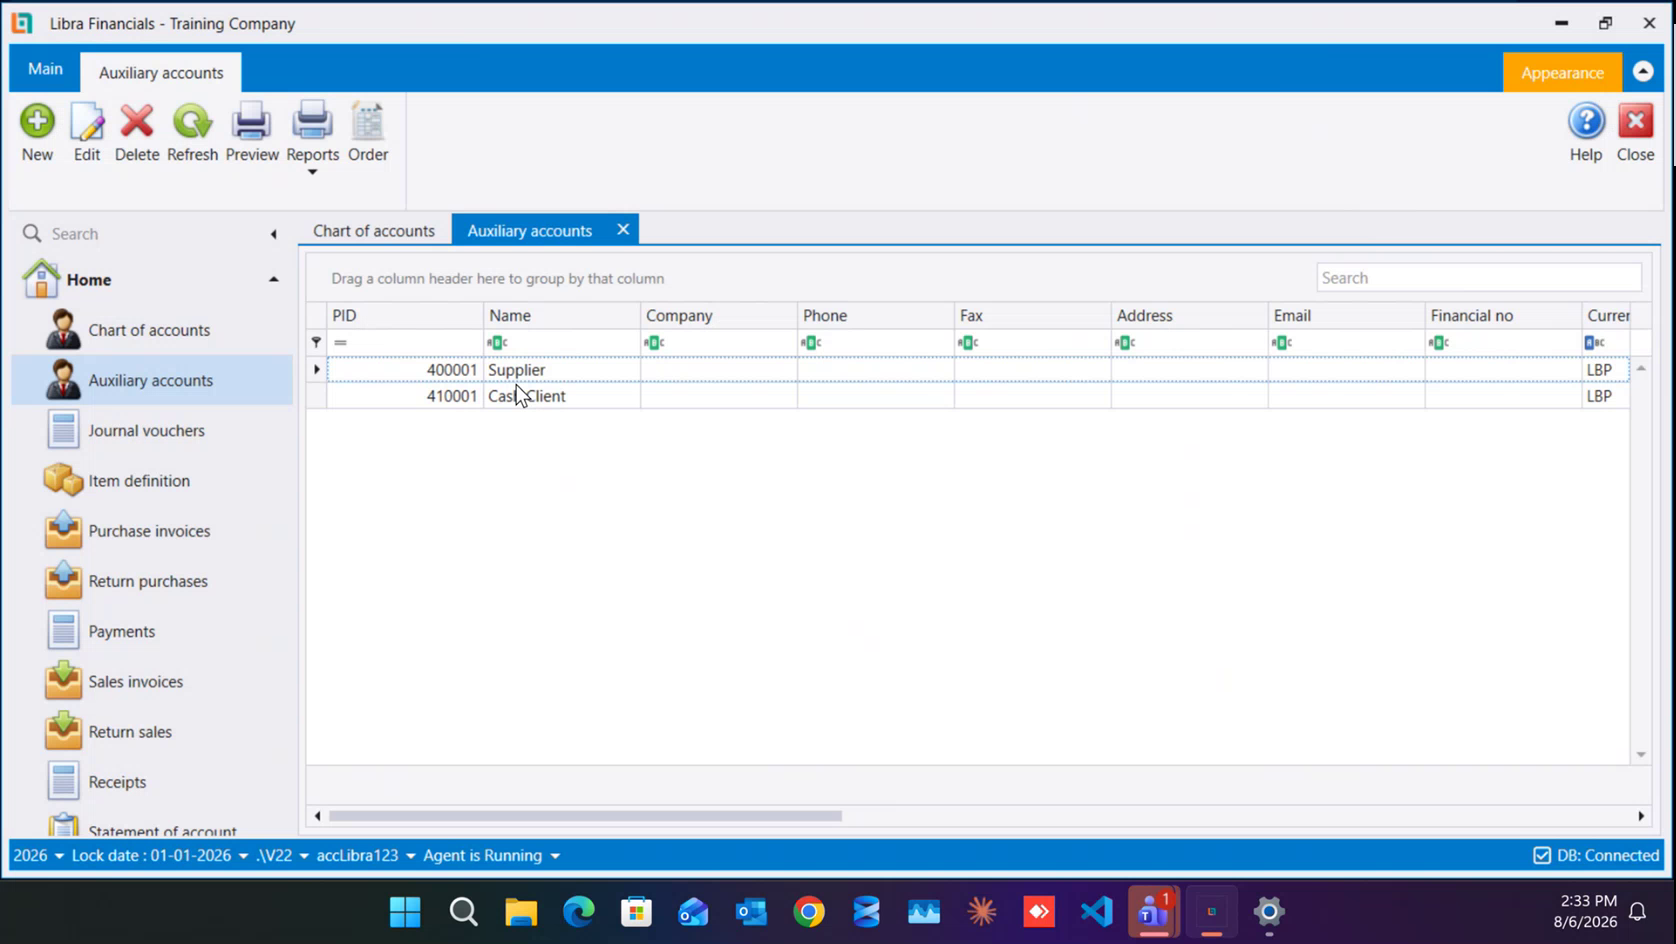
Creating a partner or an employee follows the same New → pick the List → pick the Account → fill → Save cycle as a client, on the same screen - which is why the list of auxiliary records holds suppliers and clients and staff side by side, each with an Id grouped by its family.
Why this matters
Getting these two right at the start keeps the chart clean for good:
- the owner's capital and drawings go through the partner account (4515);
- salaries and staff balances go through the employee account.
And remember the parent/child rule from the chart of accounts: once anything has been posted on an account it can never take children, so restructuring these after a year of postings is not a small job. Set them up properly now.
Next: The Auxiliary Accounts screen for the fields.
الشركاء والموظفون حسابات مساعدة (Auxiliary accounts) أيضًا - السجل نفسه، في شاشة الحسابات المساعدة نفسها التي يُنشأ فيها كل زبون ومورد. ولا يتغير إلا الحساب الذي تحتهم.
المالك شريك، وليس زبونًا أبدًا
هذا أكثر ما يُخطأ فيه عند إعداد شركة لأول مرة، ويستحق الصراحة: حساب المالك الشخصي حساب شركاء، لا حساب زبون ولا حساب مورد.
فحساب المالك الجاري - ما يضعه وما يسحبه - مكانه 4515، حساب الشركاء الجاري، تحت 45 الشركاء (Partners). وقيده كزبون يجعل المالك يبدو مدينًا، ويضخّم الذمم المدينة، ويفسد كل تقرير أعمار ديون وكل تقرير «أكبر 10» ستشغّله يومًا.
أما أيّ حساب فرعي تحت 4515 يقع عليه شريك بعينه فلا يستحق كثير حيرة. فالقرار المهم أن يقع على حساب شركاء؛ وحساب السجل المساعد يمكن تغييره بعد ذلك، وهو ما لا يصحّ في بنية الأب والابن في الشجرة نفسها.
أين يقعان في الشجرة
كلا الفرعين ابن للصنف 4 الذمم الدائنة والمدينة (Payables And Receivables):
| الفرع | ماذا يحمل |
|---|---|
| 42 المستخدمون (Personnel) | الموظفون. و4212 Personnel هو الحساب الذي تشير إليه سجلات الموظفين - اختر قائمة الموظفين في سجل مساعد فيكون الحساب الوحيد المعروض. ويسمّي المدرّب أيضًا 421 بوصفها مجموعة الموظفين الواقعة بينهما |
| 43 الضمان الاجتماعي (Social Security) | جانب الضمان، منفصلًا عن أجور الموظفين |
| 44 الدوائر الحكومية والعامة (Government And Public Departments) | الدولة، ومنها حسابات الضريبة |
| 45 الشركاء (Partners) | الملّاك. و4515 هو حساب الشركاء الجاري |
الموظفون
افتح سجلًا مساعدًا واحدًا لكل موظف على حساب الموظفين. فتمرّ الرواتب وأرصدة الموظفين عبر ذلك الحساب، ويصير لكل شخص كشف حساب خاص به.
والقائمة (List) هي التي تضيّق الحساب (Account). ففي السجل المساعد اختر قائمة الموظفين أولًا. ثم متى فتحت منتقي الحساب (Account) لم يعرض عليك إلا 4212 Personnel وحده - فلا سبيل إلى إيداع موظف في مكان آخر سهوًا:
وهي آلية «القائمة ← الحساب» نفسها التي يستعملها كل نوع من الأطراف؛ ولا تختلف إلا القائمة القصيرة الناتجة. راجع شاشة الحسابات المساعدة.
ولاحظ الفرق بين الحساب والسجل: الحساب صفّ واحد في الشجرة يتشاركه كل الموظفين، والسجل واحد لكل شخص. والأمر نفسه في الشركاء.
وسمِّهم على قاعدة واحدة والتزمها. فلمّا كان كل الموظفين يتشاركون حسابًا واحدًا، كان الاسم (Name) في السجل هو الشيء الوحيد الذي يميّز شخصًا عن آخر في كشف أو تقرير. فاستقرّ على الصيغة قبل أن تفتح أول سجل - والتدريب يتوقف ليحسم هذا بالذات قبل إنشاء أي سجل موظف.
شاشة واحدة لكل أنواع الأطراف
يتبع إنشاء شريك أو موظف دورة جديد ← اختر القائمة ← اختر الحساب ← املأ ← احفظ نفسها التي يُنشأ بها الزبون، وفي الشاشة نفسها - ولهذا يحمل جدول السجلات المساعدة الموردين والزبائن والموظفين جنبًا إلى جنب، لكل منهم معرّف مجمَّع حسب عائلته.
لماذا هذا مهم؟
ضبط هذين من البداية يبقي الشجرة نظيفة إلى الأبد:
- رأس مال المالك وسحوباته تمر عبر حساب الشركاء (4515)؛
- والرواتب وأرصدة الموظفين تمر عبر حساب الموظفين.
وتذكّر قاعدة الأب والابن من شجرة الحسابات: فمتى رُحِّل شيء على حساب لم يعد يقبل أبناءً أبدًا، وإعادة هيكلة هذين بعد سنة من القيود ليست عملًا صغيرًا. فاضبطهما الآن كما ينبغي.
التالي: شاشة الحسابات المساعدة لشرح الحقول.