Key rules & account quick referenceالقواعد الأساسية ومرجع الحسابات
This is the page to keep open. It holds the account numbers you will type every day and the rules that decide whether a chart of accounts stays usable after a year of postings.
The numbers are split into three groups on purpose, because they are not equally solid. The first group is what the shipped chart of accounts actually contains number, exact description, and where it sits in the tree. The second is accounts a business opens for itself. The third is the list the instructor dictates for you to memorise, which is about what to use an account for rather than about a label on screen.
1. The seven classes
Everything hangs off seven classes, under a root row 0 Chart of Accounts Tree View:
| Class | Latin description |
|---|---|
| 1 | Capital |
| 2 | Assets |
| 3 | Goods |
| 4 | Payables And Receivables |
| 5 | Current Assets |
| 6 | Expenditures |
| 7 | Income |
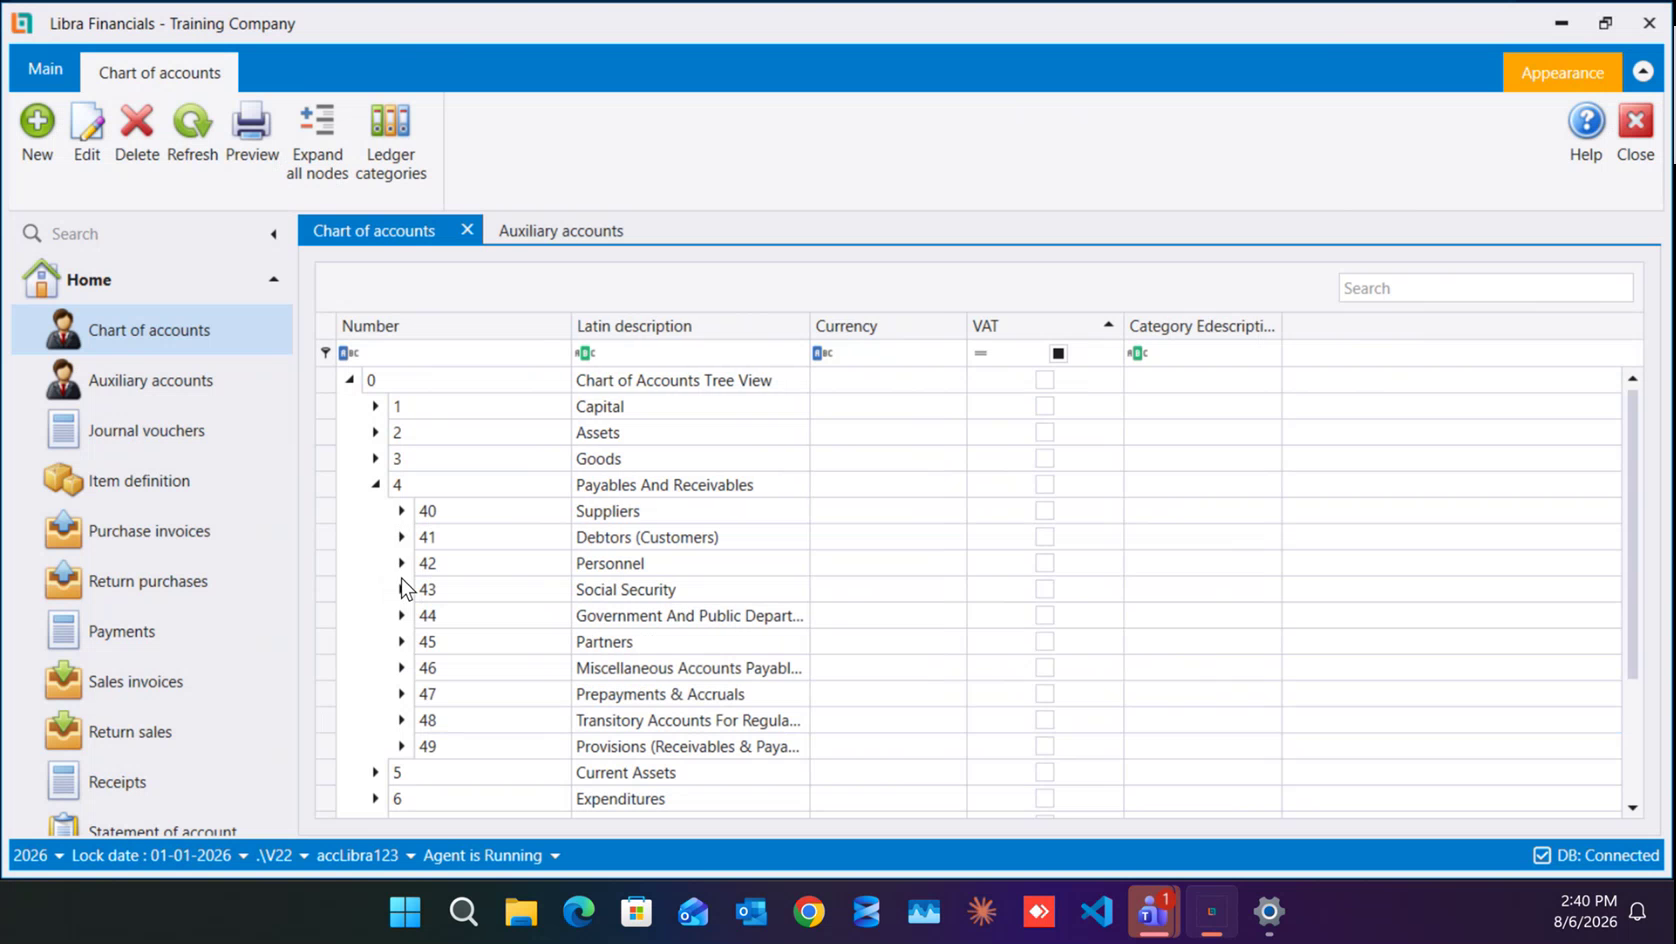
Class 4 is the one you live in, because every party you deal with sits under it:
40 Suppliers · 41 Debtors (Customers) · 42 Personnel · 43 Social Security · 44 Government And Public Departments · 45 Partners · 46 Miscellaneous Accounts Payable & Receivable · 47 Prepayments & Accruals · 48 Transitory Accounts For Regularization · 49 Provisions (Receivables & Payables)
See the chart of accounts for what the classes mean and how the digits build the structure.
2. Accounts that are in the shipped chart
Every row below was read off the tree or off an account picker.
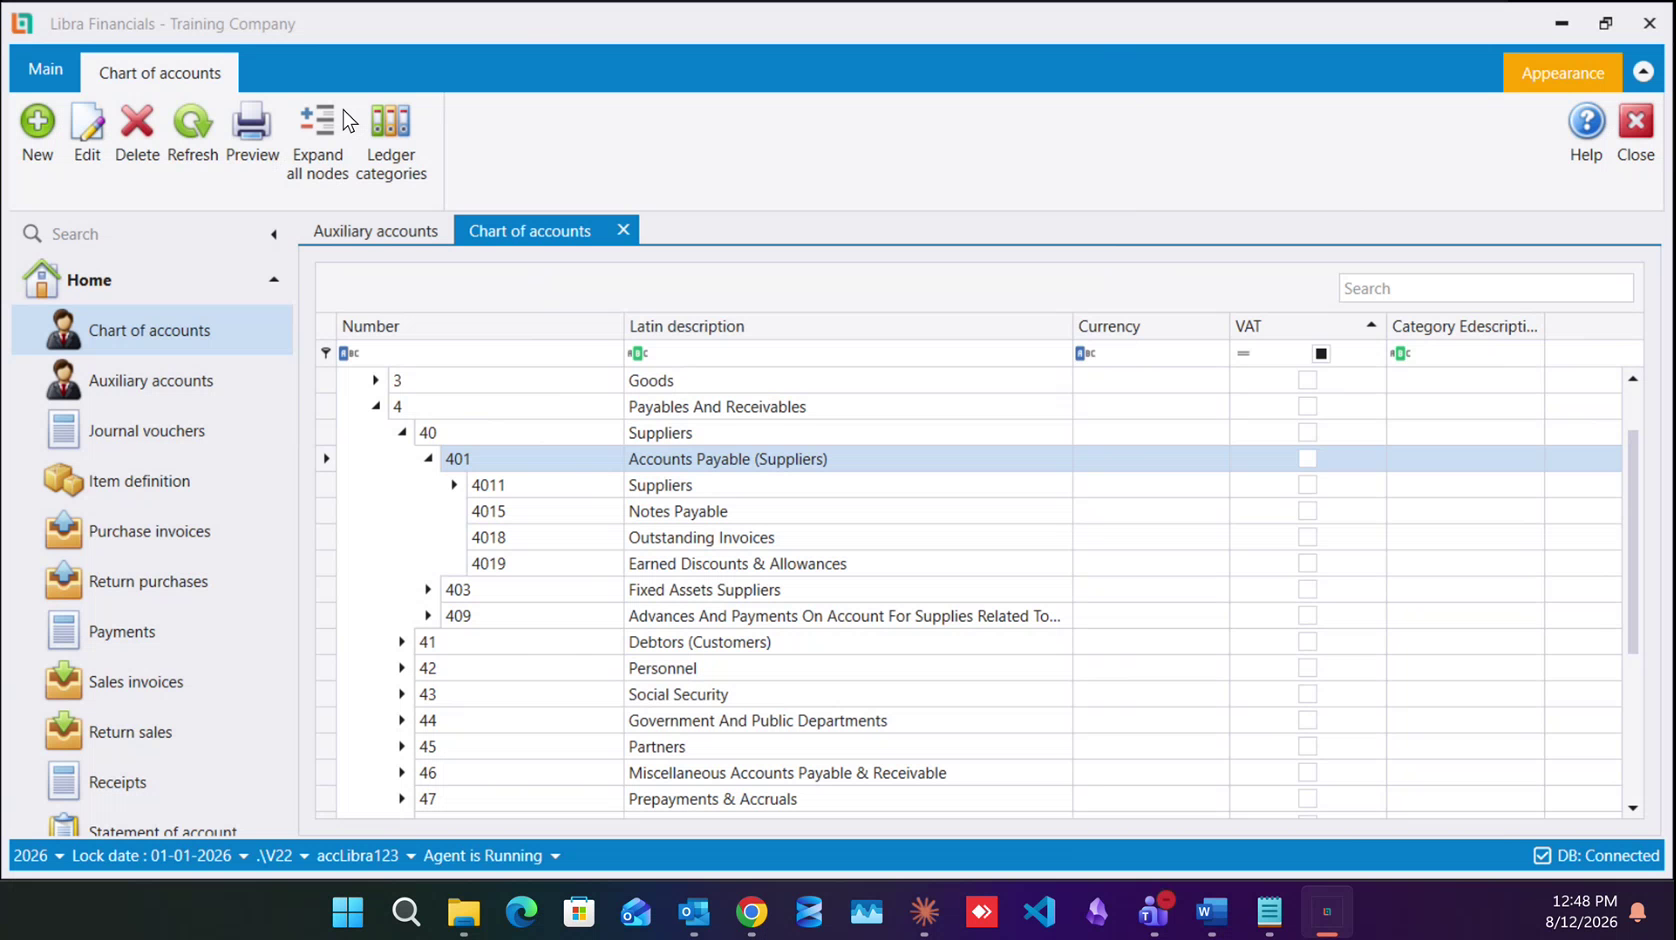
Suppliers
| Account | Latin description |
|---|---|
| 40 | Suppliers |
| 401 | Accounts Payable (Suppliers) |
| 4011 | Suppliers - a parent; do not post on it |
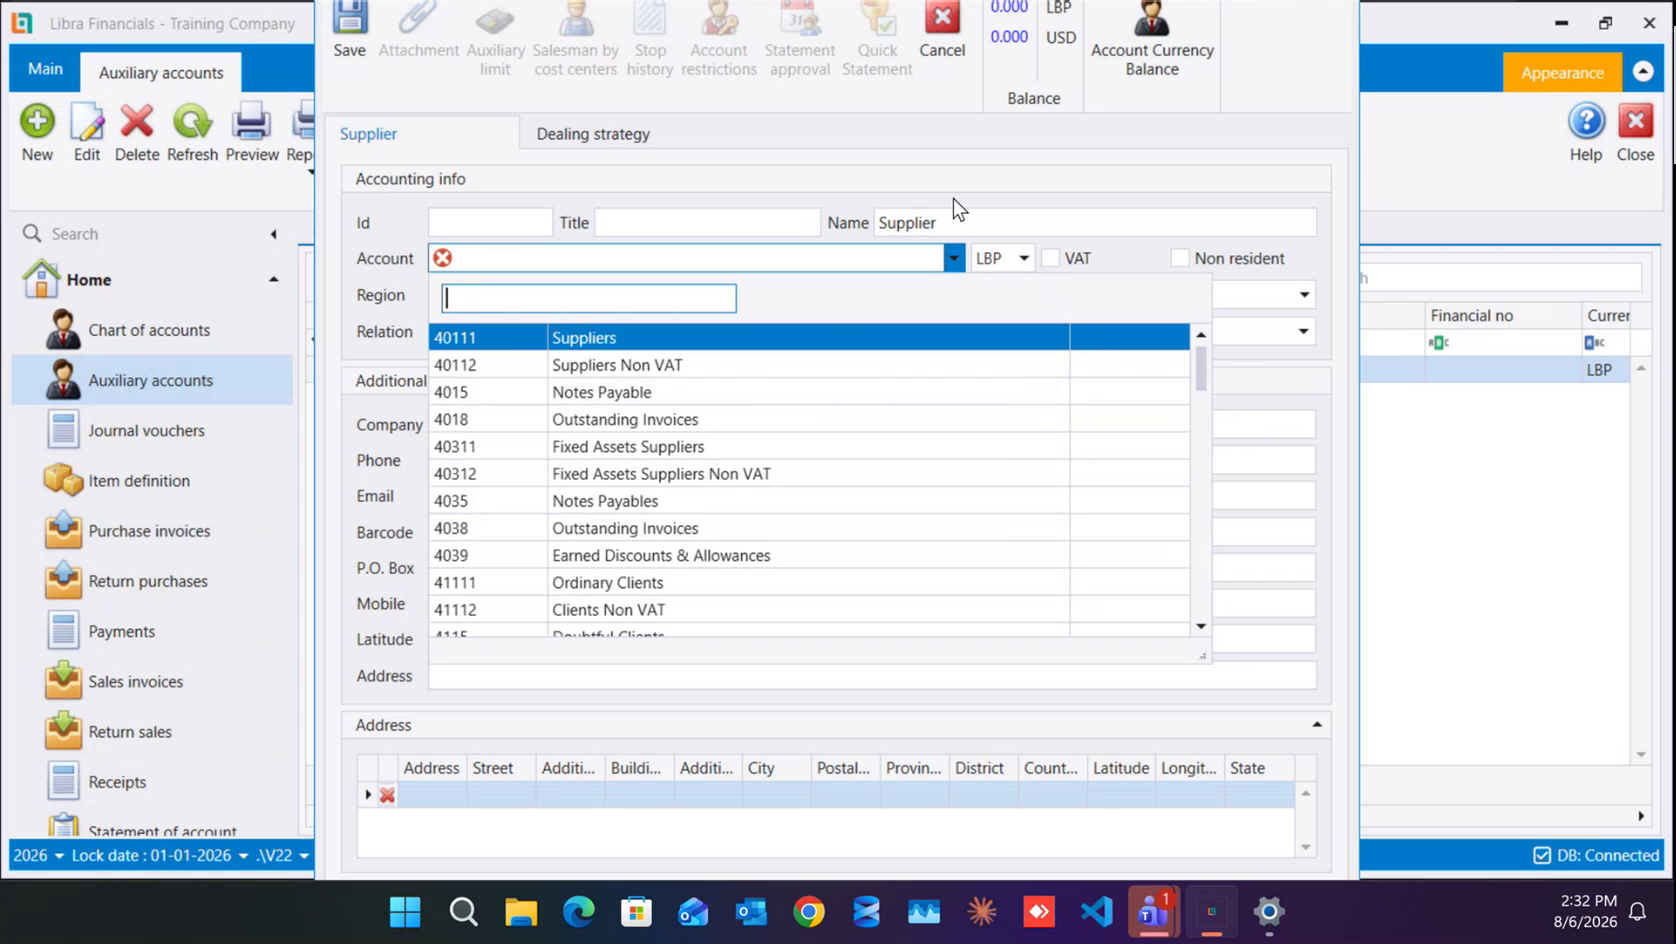
| 40111 | Suppliers (VAT) |
| 40112 | Suppliers Non VAT |
| 403 | Fixed Assets Suppliers |
| 40311 | Fixed Assets Suppliers (VAT) |
| 40312 | Fixed Assets Suppliers Non VAT |
| 4015 / 4035 | Notes Payable / Notes Payables |
| 4018 / 4038 | Outstanding Invoices |
| 4019 / 4039 | Earned Discounts & Allowances |
Clients
| Account | Latin description |
|---|---|
| 41 | Debtors (Customers) |
| 4111 | A parent; do not post on it |
| 41111 | Ordinary Clients (VAT) |
| 41112 | Clients Non VAT |
| 4115 | Doubtful Clients |
The pairing is the thing to remember: each family comes as a VAT account and a non-VAT account, and picking one of the two is what sets the VAT box on the auxiliary record for you.
Other payables
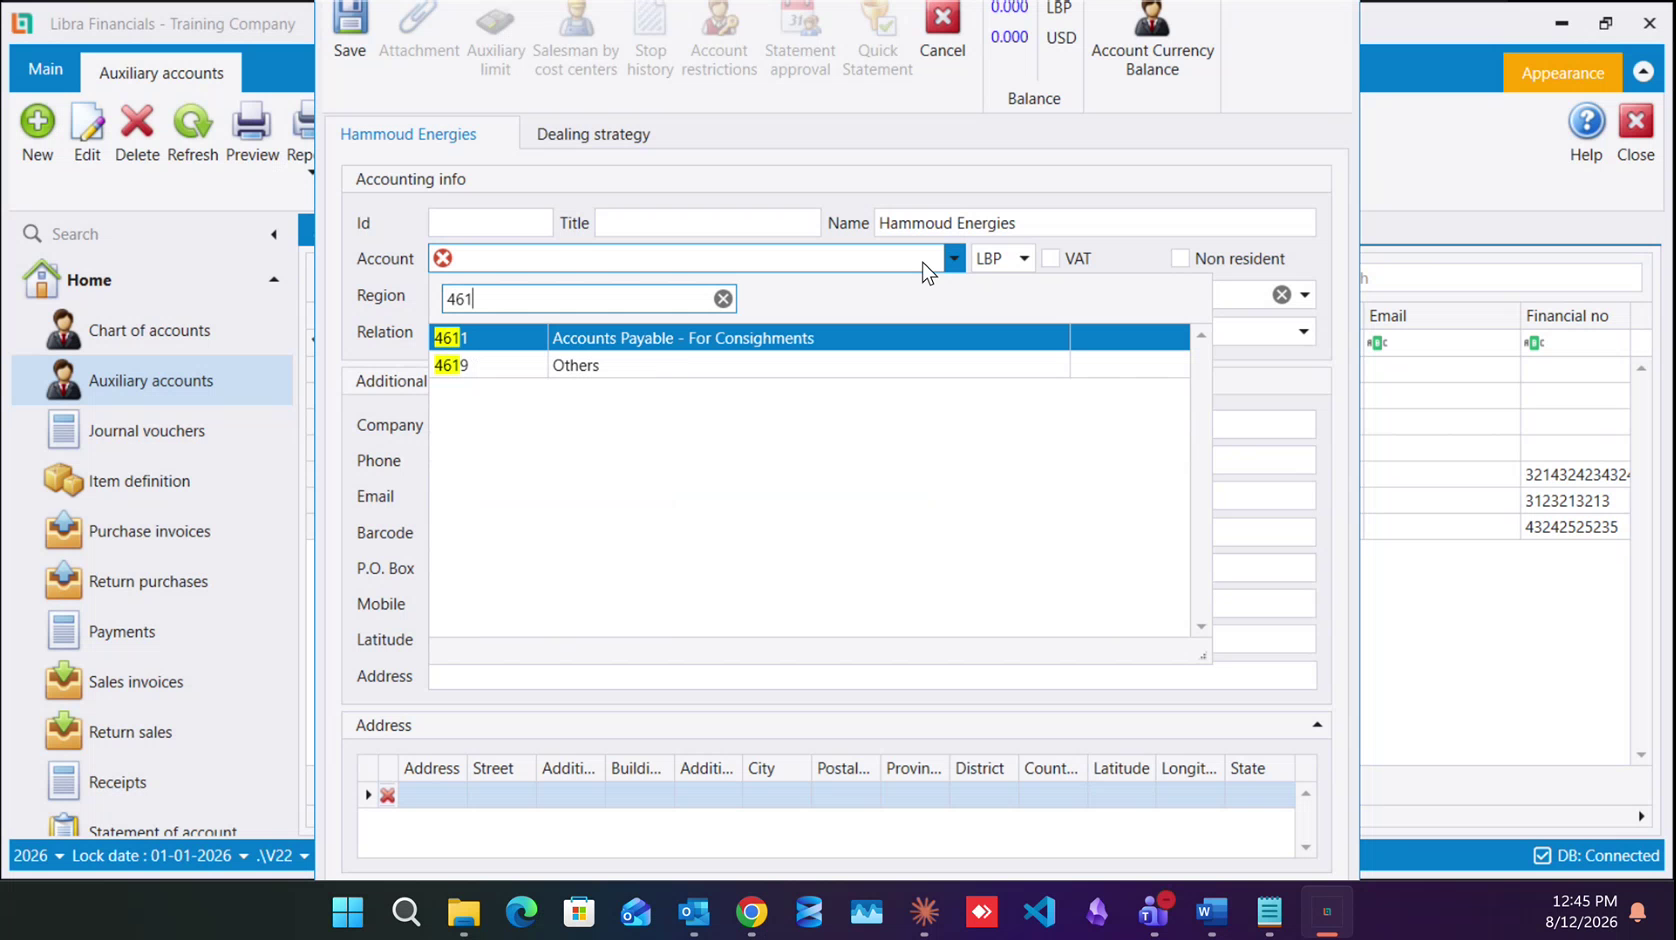
Not every party you owe money to is a supplier of goods. Class 46 carries the rest, and two of its accounts ship with the chart:
| Account | Latin description |
|---|---|
| 4611 | Accounts Payable For Consignments |
| 4619 | Others the out-of-investment expense account: bought, never resold |
| 4651 | Payable On Acquisition of Securities For Placement |
4619 is the one to memorise. Its shipped description is the single word Others, which is why the training names it by its meaning ( out-of-investment expenses ) rather than by its label.
Personnel and partners
| Account | Latin description |
|---|---|
| 42 | Personnel |
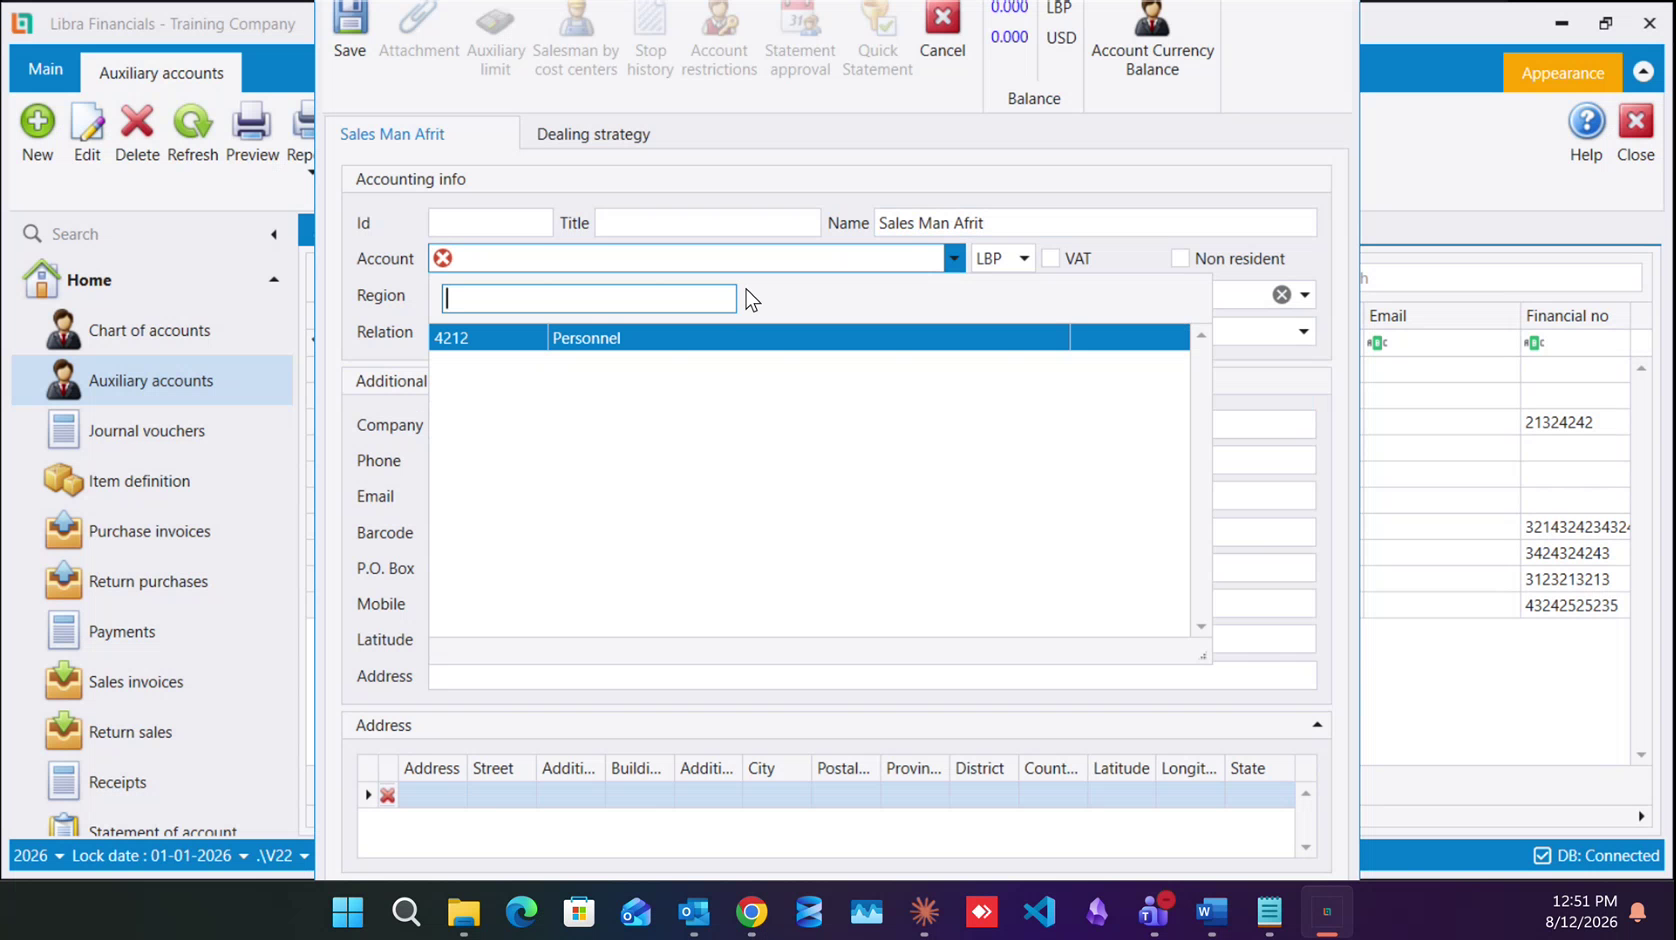
| 4212 | Personnel: The account employee records point at |
| 45 | Partners |
With List set to the employee list, the account picker offers exactly one account: 4212 Personnel. That is the whole confirmable chain - 42 Personnel → 4212 Personnel.
The instructor also dictates 421 as the employees group (session 1, 45:28). 421 sits between the two, but no screen in the training expands it, so its description is not printed here.
Banks and cash
| Account | Latin description |
|---|---|
| 5 | Current Assets |
| 50 | Security Placements (Short Term) |
| 51 | Financial Institutions |
| 511 | Checks & Coupons For Collection |
| 512 | Banks |
| 519 | Financial Institutions |
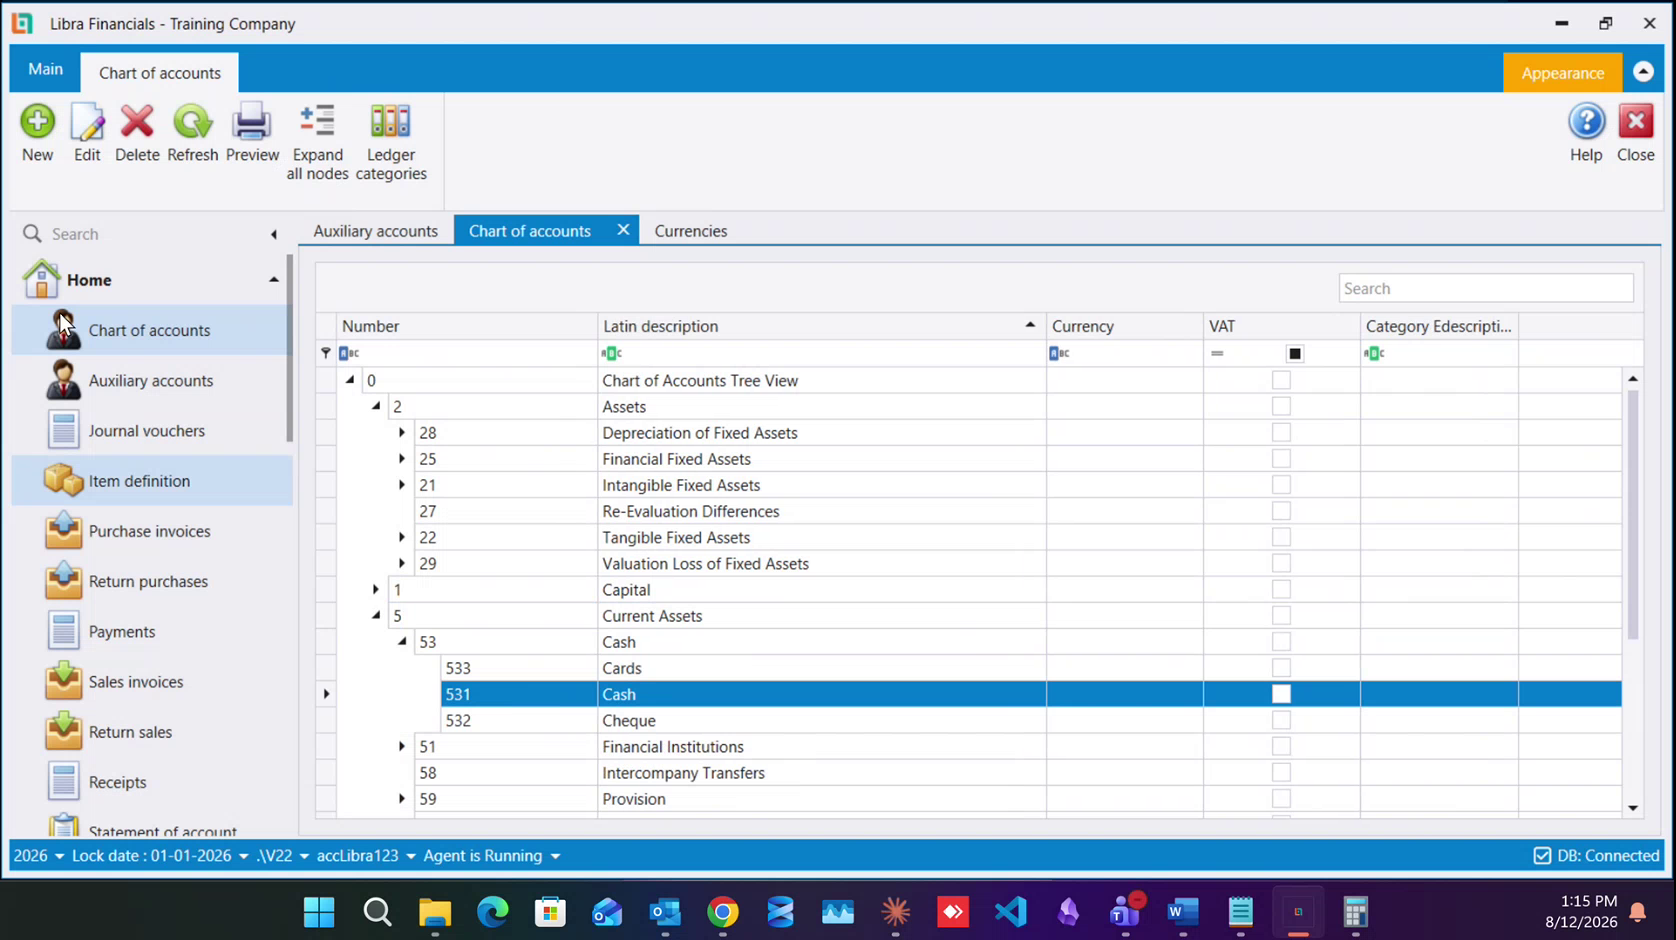
| 53 | Cash |
| 531 | Cash |
| 532 | Cheque |
| 533 | Cards |
| 58 | Intercompany Transfers |
| 59 | Provision |
Note that 512 is two levels down [ 5 Current Assets → 51 Financial Institutions → 512 Banks ] not a top-level "cash and banks" class.
See Banks and Currencies & cash.
VAT
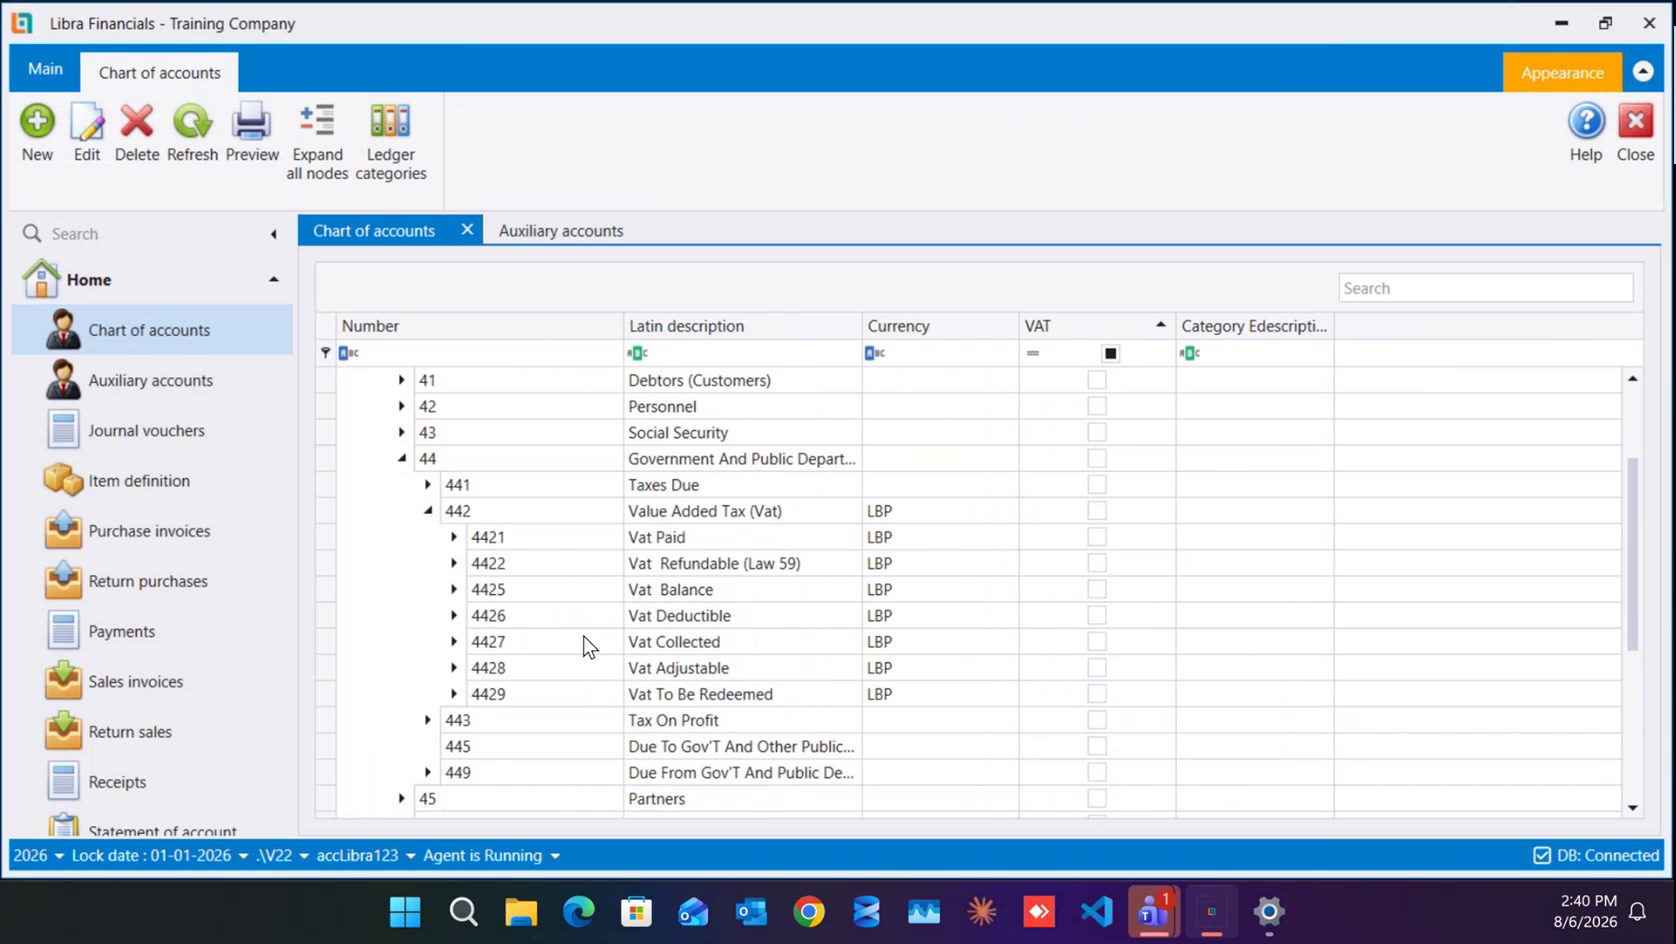
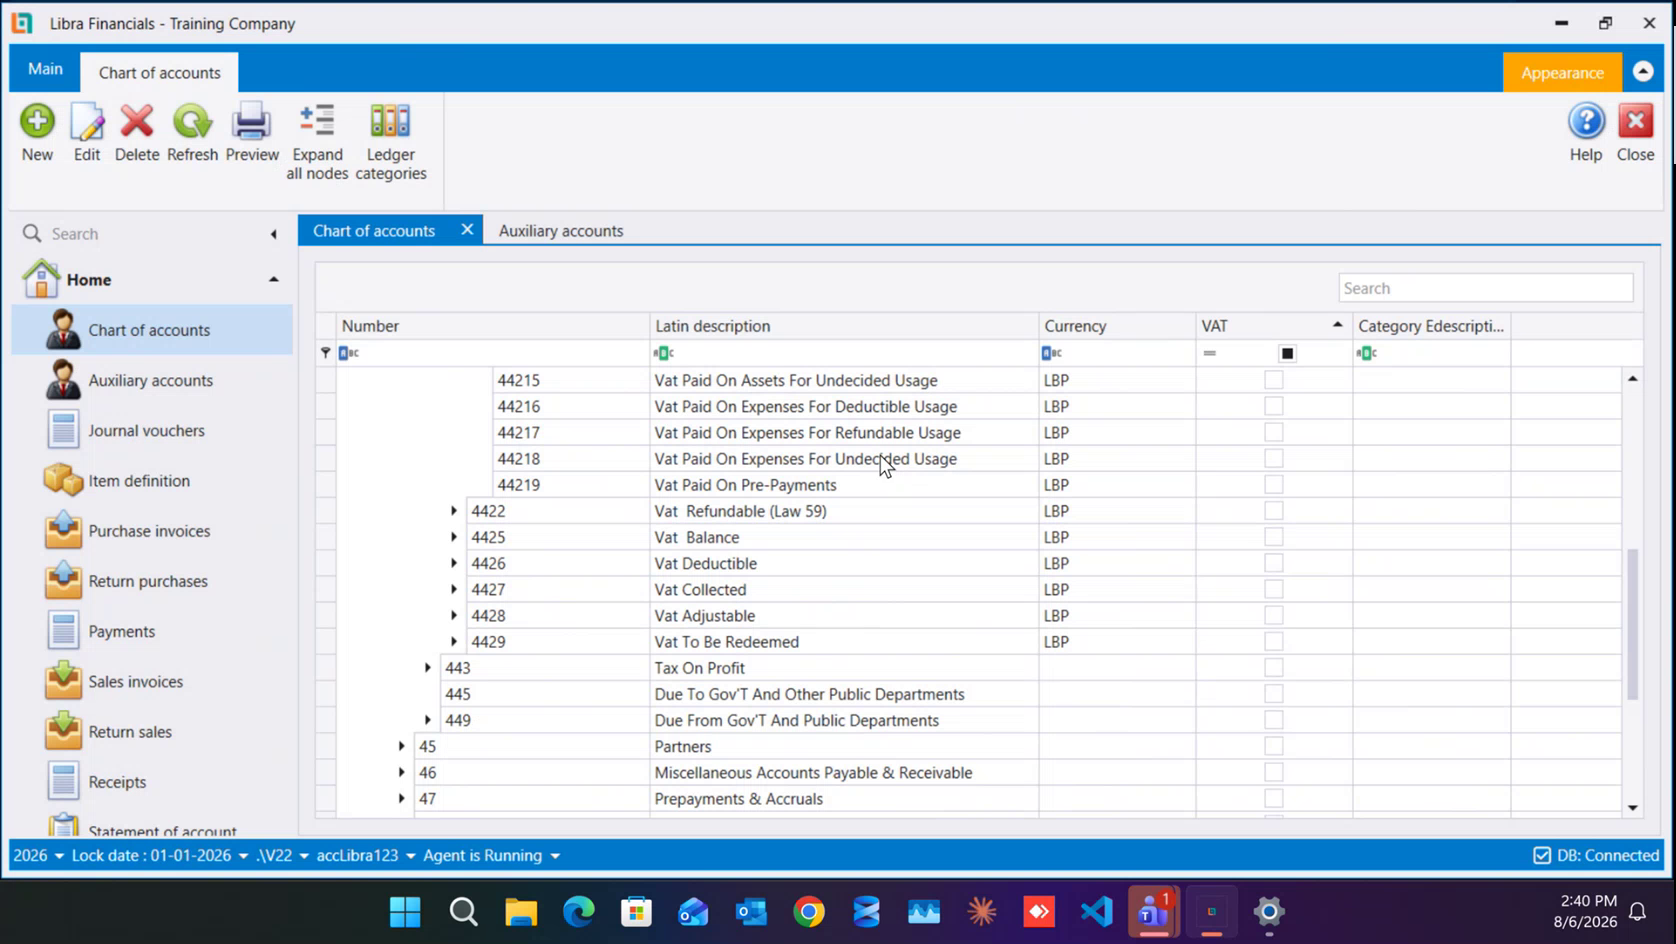
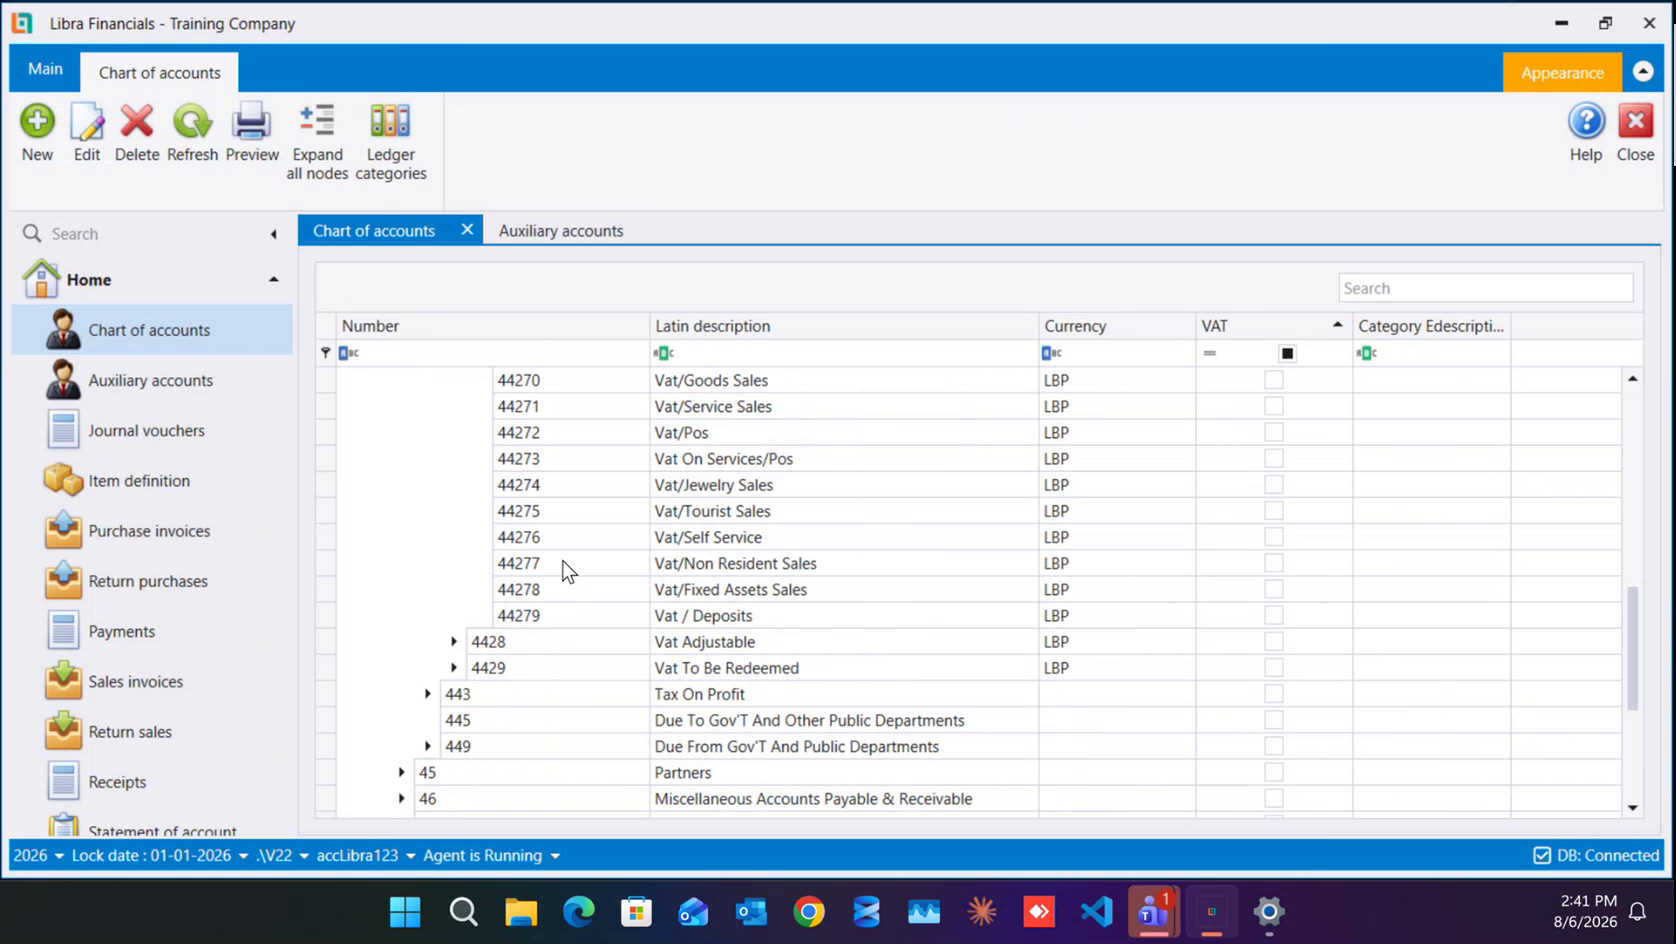
The VAT accounts all hang off 44 Government And Public Departments:
| Account | Latin description |
|---|---|
| 441 | Taxes Due |
| 442 | Value Added Tax (Vat) |
| 4421 | Vat Paid |
| 44210 | Vat Paid On Products For Deductible Usage - VAT on purchases |
| 44211 / 44212 | Vat Paid On Products For Refundable / Undecided Usage |
| 44213 / 44214 / 44215 | Vat Paid On Assets For Deductible / Refundable / Undecided Usage |
| 44216 | Vat Paid On Expenses For Deductible Usage - VAT on expenses |
| 44217 / 44218 | Vat Paid On Expenses For Refundable / Undecided Usage |
| 44219 | Vat Paid On Pre-Payments |
| 4422 | Vat Refundable (Law 59) |
| 4425 | Vat Balance: the VAT you owe or are owed; the instructor names it by that meaning rather than by this label |
| 4426 | Vat Deductible |
| 4427 | Vat Collected |
| 44270 | Vat/Goods Sales - VAT on sales |
| 44271 / 44272 / 44273 | Vat/Service Sales · Vat/Pos · Vat On Services/Pos |
| 44274 – 44279 | Jewelry · Tourist · Self Service · Non Resident · Fixed Assets Sales · Deposits |
| 4428 / 4429 | Vat Adjustable / Vat To Be Redeemed |
| 443 | Tax On Profit |
| 445 / 449 | Due To / Due From Gov'T And Public Departments |
Income - the class 7 accounts you sell on
Read from the shipped chart on screen, so the descriptions below are the product's own:
| Account | Latin description |
|---|---|
70 | Sales of Goods |
701 | Invoices - the parent your sales invoices post under |
7011 | Sales of Vat Items |
7012 | Sales of Non Vat It… (with 70121 / 70122 Exempted Sales) |
7013 / 7014 | Sales / Vat Calculat… · Sales / Deductible… |
709 | Discounts & Allow… - the same split again, for discounts you give |
71 | Sales of Products - and services live here, not under 70 |
713 | Services |
7131 | Services Subject To… |
7132 | Services Not Subje… (with 71321 / 71322 Exempted Services) |
7133 | Services With Dedu… |
The VAT column on the account is what marks subject from non-subject, exactly as it does on 40111 / 40112. Descriptions ending in … are wider than the Latin description column and are shown cut off on screen.
Full walkthrough: Income accounts.
Purchases - the other half of the pair
| Account | Latin description |
|---|---|
60111 | Purchases of Goods /Vat Deductible |
Read off a live item's Purchase account, where it sits opposite 7011 - Sales of Vat Items. That pairing - 7011 selling, 60111 buying - is the standard one for a VAT-subject good, and it is what an item family fills in for you. See Item families.
Item VAT rates
Not an account, but the number people get wrong. An item's VAT field is a rate chosen from three, not a subject/exempt tick:
| Value | Description on screen |
|---|---|
0.000 | أصناف غير خاضعة - not subject |
10.000 | أصناف خاضعة 10% - subject at 10% |
11.000 | أصناف خاضعة 11% - subject at 11% |
11 is the current Lebanese rate, and it covers most goods and every service. 0 is for the staples the state exempts. See The item definition screen.
3. Accounts a business opens for itself
These are not in the shipped chart. The training builds them for one specific business, and yours may need a different split - or none at all. They are listed because a customer who followed the training will have them and will name them at you.
| Account | What it was opened for |
|---|---|
| 5121 / 5122 / 5123 | Bank Local / Bank Foreingh / Bank E-Wallets - splitting 512 three ways |
| 5311 / 5312 | Grand Cash and Petty Cash, opened under the shipped 531 Cash |
| 535 / 539 | POS Cash and Cash Van, opened beside 531 under 53 |
| 40113 | a foreign supplier, split off from the supplier accounts |
| 40314 | a supplier of fixed assets, split off the same way |
| 46591 / 46592 | Other Supplier with VAT / Other Supplier Nont Vat - 4659 split in two so shipping and clearing can be booked with and without VAT. The typo is in the shipped chart |
Before opening any of these, read the parent/child rule in section 5. Splitting an account is only possible while nothing has been posted on it.
4. Numbers the instructor tells you to memorise
The last part of session 1 is a dictation: the accounts you will reach for so often that you should know them by heart. These are given as what to use an account for, and the description you are told is the use, not necessarily the label printed in the chart - so check each one against your own chart before you rely on it.
The sales numbers from that dictation have since been read off the screen and now appear with their real descriptions under Income in section 2 - 70 is Sales of Goods while 701 is Invoices, and 713 Services sits under 71, not under 70. See Income accounts. The purchases side went the same way: 601 is dictated, but 60111 Purchases of Goods /Vat Deductible has since been read off a live item and moved into section 2.
| Account | What it is used for |
|---|---|
| 63 | salaries |
| 64 | taxes |
| 138 / 139 | the result of the year - profit / loss |
| 4515 | the partners' current account - the owner's own money in and out |
| 4659 | other suppliers - the parent the training splits for shipping, customs and clearing |
4515 is worth singling out: the owner is a partner, never a customer. See Partners & employees.
5. The rules in one place
- New Plan always. Old Plan (full/basic chart) is legacy.
- The owner is a partner (4515), never a customer.
- Non-resident = foreign, or no fiscal number → excluded from top-10.
- PID rule - things that multiply (POS, safes, vans) get a PID; fixed things do not. Once one entry has gone through the account, the setting can no longer be changed.
- Currency base - LBP at 90,000/USD; other currencies set against LBP.
- Post only on the child account, never the parent; a used account is locked from restructuring.
- Production for make/dismantle; accumulation for fixed bundles.
- Consignment - separate warehouse per consignor; purchase only on the consignor's invoice.
- Pick the
Listbefore theAccounton an auxiliary record - it filters the account list to the accounts that kind of party may sit on, and it locks the moment you save.
هذه الصفحة التي تُبقيها مفتوحة. فيها أرقام الحسابات التي ستكتبها كل يوم، والقواعد التي تقرّر أتبقى شجرة الحسابات صالحة للاستعمال بعد سنة من القيود أم لا.
والأرقام مقسومة إلى ثلاث مجموعات عن قصد، لأنها ليست في درجة واحدة من الرسوخ. فالمجموعة الأولى هي ما تحويه شجرة الحسابات المشحونة فعلًا: الرقم، والوصف بالحرف، وموقعه في الشجرة. والثانية حسابات تفتحها الشركة لنفسها. والثالثة القائمة التي يمليها المدرّب لتحفظها، وهي عن ما يُستعمل الحساب له لا عن تسمية على الشاشة.
1. الأصناف السبعة
كل شيء معلّق على سبعة أصناف، تحت صفّ جذر 0 Chart of Accounts Tree View:
| الصنف | الوصف اللاتيني |
|---|---|
| 1 | رأس المال (Capital) |
| 2 | الأصول (Assets) |
| 3 | البضاعة (Goods) |
| 4 | الذمم الدائنة والمدينة (Payables And Receivables) |
| 5 | الأصول المتداولة (Current Assets) |
| 6 | النفقات (Expenditures) |
| 7 | الإيرادات (Income) |
والصنف 4 هو الذي تعيش فيه، لأن كل طرف تتعامل معه يقع تحته:
40 Suppliers · 41 Debtors (Customers) · 42 Personnel · 43 Social Security · 44 Government And Public Departments · 45 Partners · 46 Miscellaneous Accounts Payable & Receivable · 47 Prepayments & Accruals · 48 Transitory Accounts For Regularization · 49 Provisions (Receivables & Payables)
وراجع شجرة الحسابات لمعنى الأصناف وكيف تبني الأرقامُ البنيةَ.
2. حسابات موجودة في الشجرة المشحونة
كل صفّ أدناه مقروء من الشجرة أو من قائمة اختيار الحساب.
الموردون
| الحساب | الوصف اللاتيني |
|---|---|
| 40 | Suppliers |
| 401 | Accounts Payable (Suppliers) |
| 4011 | Suppliers - حساب أب، لا تُرحِّل عليه |
| 40111 | Suppliers (خاضع للضريبة) |
| 40112 | Suppliers Non VAT |
| 403 | Fixed Assets Suppliers |
| 40311 | Fixed Assets Suppliers (خاضع للضريبة) |
| 40312 | Fixed Assets Suppliers Non VAT |
| 4015 / 4035 | Notes Payable / Notes Payables |
| 4018 / 4038 | Outstanding Invoices |
| 4019 / 4039 | Earned Discounts & Allowances |
الزبائن
| الحساب | الوصف اللاتيني |
|---|---|
| 41 | Debtors (Customers) |
| 4111 | - حساب أب، لا تُرحِّل عليه |
| 41111 | Ordinary Clients (خاضع للضريبة) |
| 41112 | Clients Non VAT |
| 4115 | Doubtful Clients |
والاقتران هو ما يجب تذكّره: كل عائلة تأتي بحساب خاضع للضريبة وآخر غير خاضع، واختيارك أحدهما هو ما يضبط لك مربع الضريبة (VAT) في السجل المساعد.
ذمم دائنة أخرى
ليس كل طرف تدين له مورد بضاعة. فالصنف 46 يحمل الباقي، وحسابان منه يأتيان مع الشجرة المشحونة:
| الحساب | الوصف اللاتيني |
|---|---|
| 4611 | Accounts Payable - For Consignments |
| 4619 | Others - حساب مصاريف خارج الاستثمار: يُشترى ولا يُباع |
| 4651 | Payable On Acquisition of Securities For Placement |
و4619 هو الذي يجب حفظه. ووصفه المشحون كلمة واحدة هي Others، ولهذا يسمّيه التدريب بمعناه - مصاريف خارج الاستثمار - لا بتسميته على الشاشة.
المستخدمون والشركاء
| الحساب | الوصف اللاتيني |
|---|---|
| 42 | Personnel |
| 4212 | Personnel - الحساب الذي تشير إليه سجلات الموظفين |
| 45 | Partners |
فحين تُضبط القائمة (List) على قائمة الموظفين تعرض قائمةُ الحسابات حسابًا واحدًا فقط: 4212 Personnel. وهذه هي السلسلة القابلة للتأكيد كلها - 42 Personnel ← 4212 Personnel.
ويملي المدرّب أيضًا 421 بوصفها مجموعة الموظفين (الجلسة الأولى، 45:28). و421 تقع بين الاثنين، لكن لا شاشة في التدريب تفتحها، فلم يُطبع وصفها هنا.
المصارف والنقد
| الحساب | الوصف اللاتيني |
|---|---|
| 5 | Current Assets |
| 50 | Security Placements (Short Term) |
| 51 | Financial Institutions |
| 511 | Checks & Coupons For Collection |
| 512 | Banks |
| 519 | Financial Institutions |
| 53 | Cash |
| 531 | Cash |
| 532 | Cheque |
| 533 | Cards |
| 58 | Intercompany Transfers |
| 59 | Provision |
ولاحظ أن 512 على مستويين تحت - 5 Current Assets ← 51 Financial Institutions ← 512 Banks - لا صنفًا أعلى اسمه «النقد والمصارف».
وراجع المصارف والعملات والصناديق.
الضريبة على القيمة المضافة
حسابات الضريبة كلها معلّقة على 44 Government And Public Departments:
| الحساب | الوصف اللاتيني |
|---|---|
| 441 | Taxes Due |
| 442 | Value Added Tax (Vat) |
| 4421 | Vat Paid |
| 44210 | Vat Paid On Products For Deductible Usage - ضريبة المشتريات |
| 44211 / 44212 | Vat Paid On Products For Refundable / Undecided Usage |
| 44213 / 44214 / 44215 | Vat Paid On Assets For Deductible / Refundable / Undecided Usage |
| 44216 | Vat Paid On Expenses For Deductible Usage - ضريبة المصاريف |
| 44217 / 44218 | Vat Paid On Expenses For Refundable / Undecided Usage |
| 44219 | Vat Paid On Pre-Payments |
| 4422 | Vat Refundable (Law 59) |
| 4425 | Vat Balance - وهو ما يسميه المدرّب «الضريبة المستحقة»، أي الضريبة لك أو عليك |
| 4426 | Vat Deductible |
| 4427 | Vat Collected |
| 44270 | Vat/Goods Sales - ضريبة المبيعات |
| 44271 / 44272 / 44273 | Vat/Service Sales · Vat/Pos · Vat On Services/Pos |
| 44274 – 44279 | المجوهرات · السياحية · الخدمة الذاتية · غير المقيمين · مبيعات الأصول الثابتة · الودائع |
| 4428 / 4429 | Vat Adjustable / Vat To Be Redeemed |
| 443 | Tax On Profit |
| 445 / 449 | Due To / Due From Gov'T And Public Departments |
الإيرادات - حسابات الصنف 7 التي تبيع عليها
مقروءة من الشجرة المشحونة على الشاشة، فالأوصاف أدناه أوصاف المنتج نفسه:
| الحساب | الوصف اللاتيني |
|---|---|
70 | Sales of Goods - مبيعات البضاعة |
701 | Invoices - الأب الذي تُرحَّل تحته فواتير بيعك |
7011 | Sales of Vat Items |
7012 | Sales of Non Vat It… (ومعه 70121 / 70122 Exempted Sales) |
7013 / 7014 | Sales / Vat Calculat… · Sales / Deductible… |
709 | Discounts & Allow… - التقسيم نفسه مرة أخرى، للحسومات التي تمنحها |
71 | Sales of Products - والخدمات تعيش هنا، لا تحت 70 |
713 | Services |
7131 | Services Subject To… |
7132 | Services Not Subje… (ومعه 71321 / 71322 Exempted Services) |
7133 | Services With Dedu… |
وعمود VAT على الحساب هو ما يميّز الخاضع من غير الخاضع، تمامًا كما يفعل على 40111 / 40112. والأوصاف المنتهية بـ … أعرض من عمود الوصف اللاتيني (Latin description) فتظهر مقطوعة على الشاشة.
والشرح الكامل: حسابات الإيرادات.
المشتريات - النصف الآخر من الزوج
| الحساب | الوصف اللاتيني |
|---|---|
60111 | Purchases of Goods /Vat Deductible |
قُرئ عن Purchase account في صنف حيّ، حيث يجلس مقابل 7011 - Sales of Vat Items. وهذا الاقتران - 7011 للبيع و60111 للشراء - هو المعتاد لبضاعة خاضعة للضريبة، وهو ما تملؤه لك عائلة الصنف. راجع عائلات الأصناف.
نسب الضريبة على الأصناف
ليست حسابًا، لكنها الرقم الذي يخطئ فيه الناس. حقل VAT في الصنف نسبة تُختار من ثلاث، لا علامة خاضع/معفى:
| القيمة | الوصف على الشاشة |
|---|---|
0.000 | أصناف غير خاضعة |
10.000 | أصناف خاضعة 10% |
11.000 | أصناف خاضعة 11% |
و11 هي النسبة اللبنانية الحالية، وتشمل معظم البضائع وكل خدمة. و0 للمواد الأساسية التي تعفيها الدولة. راجع شاشة تعريف الأصناف.
3. حسابات تفتحها الشركة لنفسها
هذه ليست في الشجرة المشحونة. فالتدريب يبنيها لعمل بعينه، وقد يحتاج عملك تقسيمًا مختلفًا - أو لا يحتاج تقسيمًا أصلًا. وهي مذكورة هنا لأن الزبون الذي تابع التدريب ستكون لديه وسيذكرها لك بأرقامها.
| الحساب | لماذا فُتح |
|---|---|
| 5121 / 5122 / 5123 | Bank Local / Bank Foreingh / Bank E-Wallets - تقسيم 512 ثلاثة أقسام |
| 5311 / 5312 | Grand Cash وPetty Cash، يُفتحان تحت 531 Cash المشحون |
| 535 / 539 | POS Cash وCash Van، يُفتحان بجانب 531 تحت 53 |
| 40113 | مورد أجنبي، مفصول عن حسابات الموردين |
| 40314 | مورد أصول ثابتة، مفصول بالطريقة نفسها |
| 46591 / 46592 | Other Supplier with VAT / Other Supplier Nont Vat - قسمة 4659 إلى اثنين ليُسجَّل الشحن والتخليص خاضعًا وغير خاضع. والخطأ المطبعي في الشجرة المشحونة نفسها |
وقبل فتح أي منها اقرأ قاعدة الأب والابن في القسم 5. فتقسيم حساب ممكن فقط ما دام لم يُرحَّل عليه شيء.
4. أرقام يطلب المدرّب حفظها
آخر جزء من الجلسة الأولى إملاء: الحسابات التي ستمدّ يدك إليها كثيرًا حتى يجدر بك حفظها. وهي تُعطى بوصفها ما يُستعمل الحساب له، والوصف الذي يُملى عليك هو الاستعمال، لا بالضرورة التسمية المطبوعة في الشجرة - فتحقّق من كل واحد منها في شجرتك أنت قبل أن تعتمد عليه.
أما أرقام المبيعات في ذلك الإملاء فقد قُرئت منذُ ذلك الحين عن الشاشة، وهي تظهر الآن بأوصافها الحقيقية تحت الإيرادات في القسم 2 - فـ70 هو Sales of Goods بينما 701 هو Invoices، و713 Services يجلس تحت 71 لا تحت 70. راجع حسابات الإيرادات. وجانب المشتريات سلك الطريق نفسه: 601 مُملى، أما 60111 Purchases of Goods /Vat Deductible فقد قُرئ منذُ ذلك الحين عن صنف حيّ وانتقل إلى القسم 2.
| الحساب | فيمَ يُستعمل |
|---|---|
| 63 | الرواتب |
| 64 | الضرائب |
| 138 / 139 | نتيجة السنة - ربح / خسارة |
| 4515 | حساب الشركاء الجاري - أموال المالك دخولًا وخروجًا |
| 4659 | موردون آخرون - الأب الذي يقسمه التدريب للشحن والجمرك والتخليص |
و4515 جديرة بالإفراد: المالك شريك، وليس زبونًا أبدًا. راجع الشركاء والموظفين.
5. القواعد في مكان واحد
- الخطة الجديدة دائمًا. القديمة (المخطط الكامل/الأساسي) قديمة.
- المالك شريك (4515)، وليس زبونًا أبدًا.
- غير المقيم = أجنبي أو بلا رقم مالي ← يُستثنى من العشرة الأوائل.
- قاعدة PID - ما يتكاثر (نقاط بيع، خزن، سيارات) يأخذ PID؛ وما هو ثابت لا. ومتى مرّ قيد واحد على الحساب لم يعد الإعداد قابلًا للتغيير.
- أساس العملة - الليرة بسعر 90,000/دولار؛ وباقي العملات مقابل الليرة.
- رحّل على الحساب الابن فقط، لا على الأب؛ الحساب المستخدم يُقفل من إعادة الهيكلة.
- الإنتاج للتصنيع/التفكيك؛ والتجميع للأطقم الثابتة.
- الأمانة - مستودع مستقل لكل مودع؛ والشراء فقط عند فاتورة المودع.
- اختر
القائمة (List)قبلالحساب (Account)في السجل المساعد - فهي تُصفّي قائمة الحسابات إلى ما يجوز لذلك النوع من الأطراف الجلوس عليه، وتُقفل لحظة الحفظ.